Price Reduction vs. Seller Credit: Which Is Better for Homebuyers?
Price Reduction vs. Seller Credit: Which Is Better for Homebuyers?
You found a house you love, and there appears to be some room to negotiate.
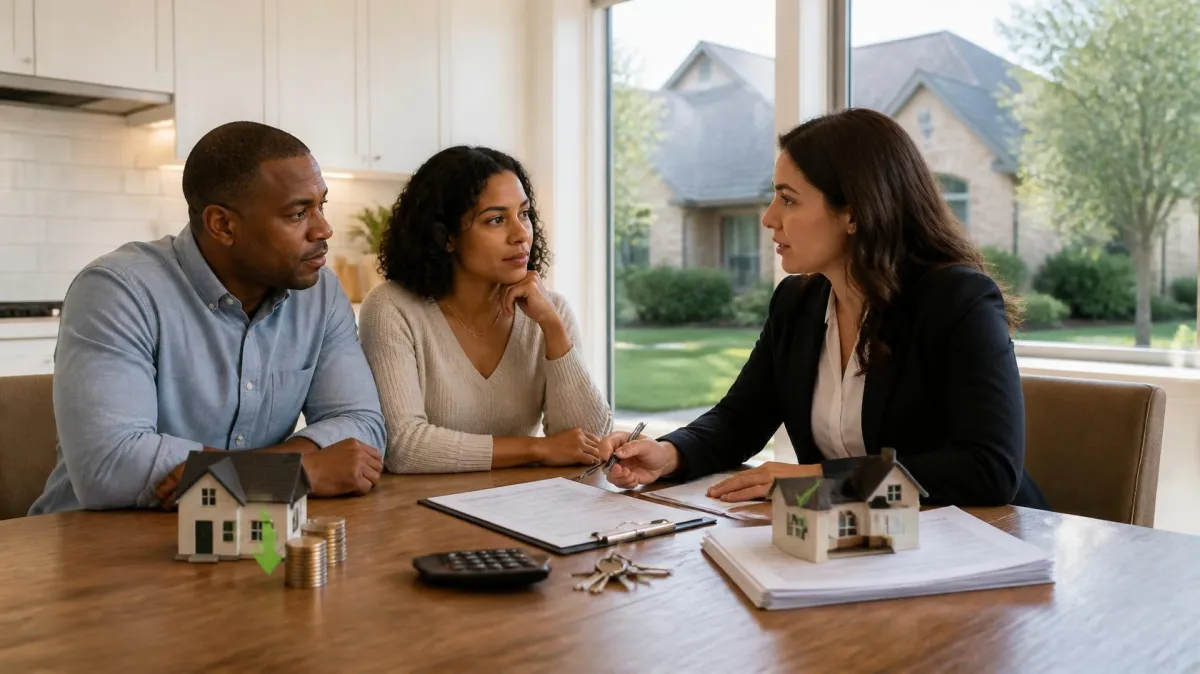
Would you rather have the seller reduce the price by $10,000 or give you a $10,000 seller credit toward eligible expenses?
A lot of buyers immediately choose the price reduction.
After all, who doesn't want to pay less for the house?
But depending on your financing and financial goals, a seller credit could potentially provide more immediate value.
This is why I don't negotiate based solely on purchase price.
I want to know what the negotiation actually does for you.
What Is a Price Reduction?
A price reduction lowers the agreed purchase price of the property.
For example:
Original price: $400,000
Negotiated price: $390,000
You are purchasing the property for $10,000 less.
That can reduce the amount you need to finance, depending on your down payment and loan structure.
It can also reduce the amount of your required down payment if that amount is calculated as a percentage of the purchase price.
Sounds great.
But there is an important detail.
A $10,000 price reduction does not mean your monthly mortgage payment drops by $10,000, or even by hundreds of dollars in every case.
The monthly principal and interest savings may be smaller than buyers expect.
What Is a Seller Credit?
Instead of reducing the price, the seller may agree to contribute toward certain eligible buyer expenses.
For example:
Purchase price: $400,000
Seller credit: $10,000
Subject to the contract, loan program, appraisal, and lender requirements, that credit may potentially be applied toward allowable costs such as:
Certain closing costs
Prepaid expenses
Escrow funding
Discount points
Eligible mortgage buydown expenses
The permitted amount and uses depend on your financing.
Why Would a Seller Credit Be Better?
Suppose your biggest concern isn't the monthly payment.
It's the amount of money you need to bring to closing.
Maybe you have your down payment saved but also need several thousand dollars for eligible closing expenses.
A negotiated seller credit could potentially reduce the amount of your own money needed for those expenses.
That could allow you to keep more cash available after closing.
Cash After Closing Matters
I don't want buyers spending every dollar they have just to get the keys.
After closing, life continues.
You may need money for:
Moving
Utility deposits
Appliances
Window coverings
Furniture
Minor repairs
Lawn equipment
Emergency savings
Having additional cash available after closing can be valuable.
This is one reason the best negotiation isn't always the lowest sales price.
When Could the Price Reduction Be Better?
There are situations where lowering the purchase price may make more sense.
For example:
You have plenty of cash for closing
You don't have enough eligible expenses to use a large credit
Your financing limits seller contributions
You want to reduce the amount financed
The lower price better supports the appraisal
Your long-term strategy favors reducing the purchase price
Every buyer is different.
What About Using the Seller Credit to Lower the Interest Rate?
This is another option worth discussing with your lender.
Depending on your loan and applicable requirements, allowable seller contributions may potentially be used toward discount points or certain rate-buydown structures.
That means the question might not simply be:
$10,000 off the house or $10,000 toward closing costs?
It might be:
Would some of that money be better used to lower my mortgage rate?
Now we have three scenarios to compare.
Scenario 1: Reduce the Purchase Price
This may reduce:
Amount financed
Required down payment in some cases
Monthly principal and interest
The exact effect depends on your loan.
Scenario 2: Use a Seller Credit Toward Eligible Closing Costs
This may reduce the amount of your own cash needed for allowable expenses at closing.
That can help preserve savings.
Scenario 3: Use Allowable Funds Toward a Rate Buydown
Depending on the financing structure, this may reduce the mortgage payment temporarily or permanently.
The cost and benefit need to be calculated by your lender.
Ask the Lender to Run the Numbers
This is where your lender becomes an important part of the negotiation strategy.
Instead of guessing, ask for side-by-side scenarios.
For example:
Option A: $400,000 purchase with $10,000 seller credit
Option B: $390,000 purchase without the credit
Then compare:
Down payment
Loan amount
Interest rate
Principal and interest
Estimated closing costs
Cash needed at closing
Total monthly payment
Now you can see which option actually helps you more.
Don't Forget Property Taxes and Insurance
A lower purchase price doesn't necessarily tell you everything about the monthly payment.
Houston-area buyers also need to consider:
Property taxes
Homeowners insurance
Mortgage insurance
HOA dues
MUD-related taxes when applicable
I want buyers comparing the total housing expense.
The Seller Is Looking at the Numbers Too
Remember that the seller is evaluating the financial effect of your offer.
A $400,000 offer with a $10,000 seller contribution is not financially identical to a $400,000 offer without one.
We need to structure the offer so it helps you while still giving the seller a reason to accept.
Market Conditions Matter
Your negotiating leverage depends partly on the property.
If the home has been listed for a while, has had price reductions, or is competing against a lot of inventory, we may have more room to negotiate.
If several buyers are competing for the property, asking for a large seller contribution may affect how your offer is viewed.
There is no universal negotiation strategy.
What About New Construction?
This comparison is particularly useful with builders.
A builder might offer:
A price reduction
Closing-cost assistance
Special financing
Discount points
Temporary rate buydown
Upgrade allowance
Don't automatically choose whichever incentive has the largest dollar amount.
Ask what each option does to:
Cash to close + monthly payment + long-term cost
That is a much better comparison.
Final Thoughts
Would I rather negotiate $10,000 off the price or a $10,000 seller credit?
My answer is:
Show me the numbers first.
If cash to close is your biggest concern, the seller credit may be more useful.
If you already have plenty of cash and want to reduce the amount financed, the price reduction may be attractive.
If monthly payment is the priority, an allowable interest-rate strategy may deserve consideration.
The best negotiation is the one that solves the problem that matters most to you.
About Marysol Calvillo
I'm a real estate broker helping buyers throughout Katy, Cypress, Hockley, 77084, 77095, and the greater Houston area.
I help my buyers look beyond the sales price and evaluate how different negotiation strategies affect their cash to close, monthly payment, and overall purchase.
Call to Action
Getting ready to make an offer on a Houston-area home? Let's look at the numbers before deciding what to negotiate. I'll work with you and your lender to compare price reductions, seller credits, and other available options so your offer supports your financial goals.